Fintiv Solution · P2C
A full card and banking program a partner can launch under their own brand
Wallet, card, and bank account, without building the plumbing first.
Overview
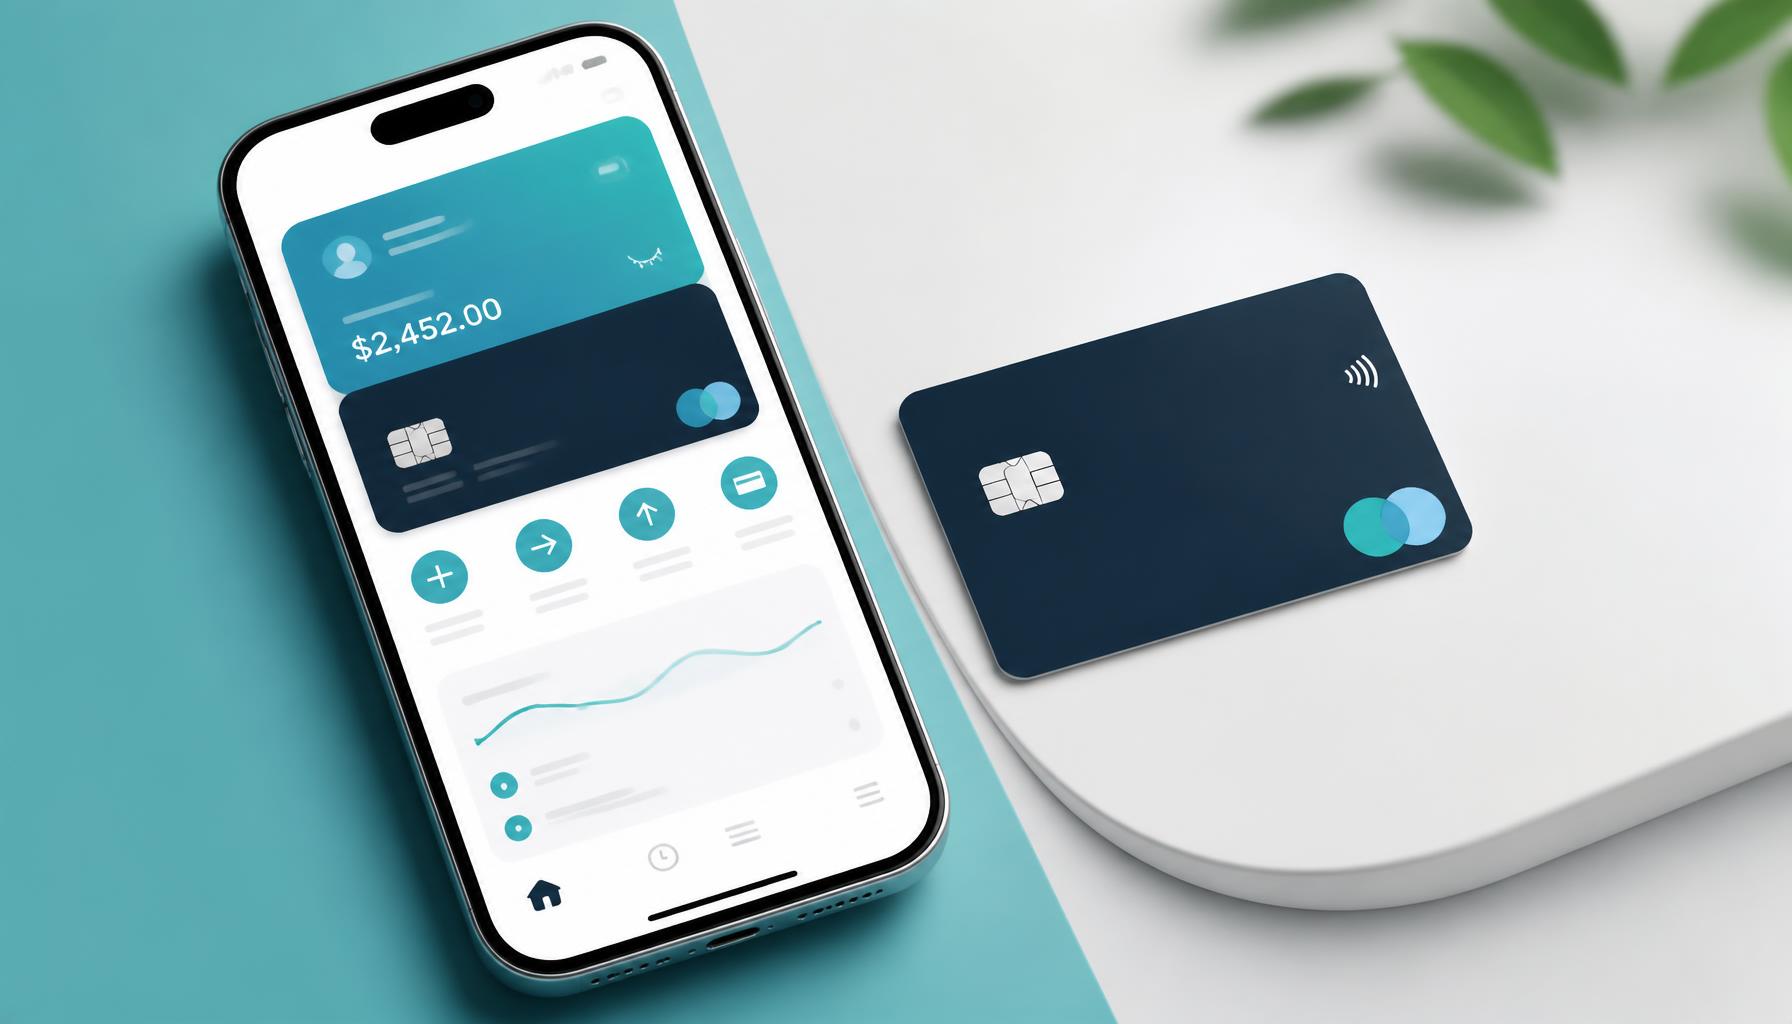
Launching a branded card program usually means years of work, a bank sponsorship relationship, a card processor, KYC and compliance infrastructure, and a mobile app to tie it together. Fintiv's P2C solution packages all of that into a single turnkey program. A partner gets a digital wallet, an instant issue virtual card, a physical debit card, and a real US bank account backed by a sponsor bank, ready to launch under their own name.
Virtual Bank Network® is the product that powers this solution, delivering the full range of card issuance and account management capabilities described above, in production and already serving real transaction volume. It combines sponsor banking, card processing, KYC, compliance, and wallet infrastructure into a single platform so a partner can go to market under its own brand without assembling the pieces independently.
Key Features
- Digital wallet with instant issue virtual card and physical debit card
- Real US bank account, backed by an established sponsor bank relationship
- Automated KYC onboarding and identity verification
- Direct deposit, inbound ACH funding, and cash loading at roughly 90,000 retail locations
- ATM payouts and international money transfer
- Average 5% instant cashback at more than 300 chain stores, restaurants, and online retailers
- Built in fundraising, savings, and bill splitting tools
- Full customer support stack, a self service portal plus live L2 and L3 teams for fraud, disputes, and chargebacks
Why It Matters
- This solution lets an enterprise capture the interchange and float revenue that comes with issuing its own card.
- It deepens the customer relationship in a way a co brand card or a third party wallet never can, because the account itself belongs to the partner's brand.
- It also removes the two hardest parts of launching a bank product, getting a sponsor bank relationship in place, and building a compliance and underwriting operation capable of running it responsibly.
- Fintiv already has both established, alongside more than 150 patents across mobile wallets and payments that back the platform.
How It Connects
Underneath the branded experience, P2C runs on the same technology as every other Fintiv solution. PHAST handles payment routing and switching, SHURE runs the underwriting rules engine, and the rewards and offers layer connects to the same ledger already tracking peer to peer transfers and merchant purchases elsewhere on the platform. A card issued through P2C isn't a separate product bolted onto the ecosystem, it's a physical and digital front door into the same one.